In some discussions for the business overview 2022, sources have expressed their various answers for this year. Sources from shipping companies mostly expect steady business this year. The freight rate is expected to stay at the level of 2021, thus giving them a good profit as they got last year. Some hope for a ‘soft landing’, not a ‘hard landing’, if there will be a rate decrease.
Meanwhile, cargo owners – represented by shippers and consignees – expect business normalization, meaning that the freight rate will be back to normal at the pre-pandemic level.
Can we predict for a conclusion how the business will be in 2022 after we pass the first month (January)?
According to data released by some analyses, the freight rate of January continued to increase, both month to month and year on year. The FBX index rose 7% from January 7 to January 28, and at a trade lane level, we saw Asia-North Europe go up by 5% and the Transpacific into US West Coast up by 14%.
Drewry composite World Container Index remains 79% higher than a year ago. The average composite index of the WCI, assessed by Drewry year-to-date, is $9,490 per 40ft container, which is $6,537 higher than the five-year average of $2,953 per 40ft container.
In essence, this was expected for two reasons. One reason is the usual seasonal demand push leading up to the Chinese New Year. The other reason is the continuing operational disruption caused by the multitude of bottlenecks in the supply chain and constricting capacity.
Will it continue until the end of this year? Some current facts may describe it for the conclusion.
Reported that carriers and shippers increasingly enter into annual contracts for 2022 at much higher levels than ever seen before, and by the signing in some cases of both two- and three-year contracts. Furthermore, charter rates for container vessels continue to increase.
On the other hand, there was no significant resistance from shippers and consignees. To explain it, they also took a good margin from this. We are presently seeing major importers in Europe and North America post highly positive results in 2021.
The shipping lines will have noted this as well if the major customers have perfectly viable business models under the rate levels seen in early 2021. Why would they want to see rate levels reduced back to pre-pandemic levels?
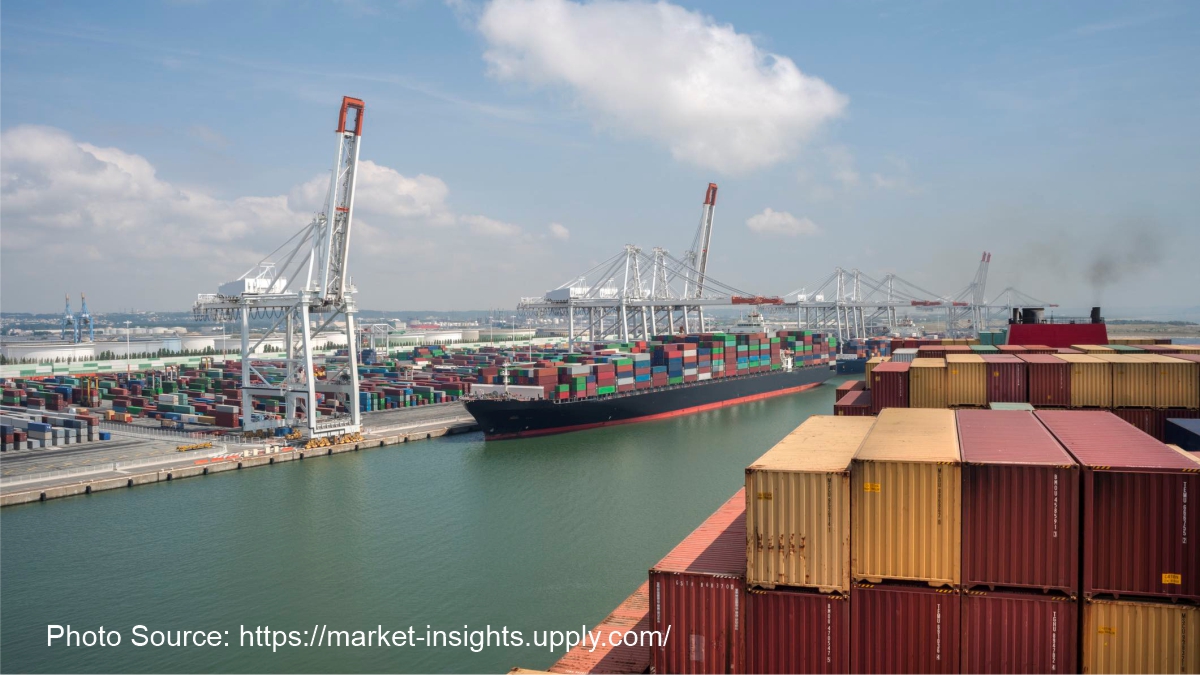
So, reflecting the existing supply chain chaos mostly created by port congestion amid the continuous pandemic outbreak on the one hand, while on the other hand, shippers will still be benefitted from the situation; we think it hard to make the business back to the pre-pandemic level.
Read ISG Cover Story February 2022: https://theshippinggazette.com/shippings-manoeuvres-to-total-logistics-worries-of-forwarders-going-spiral/