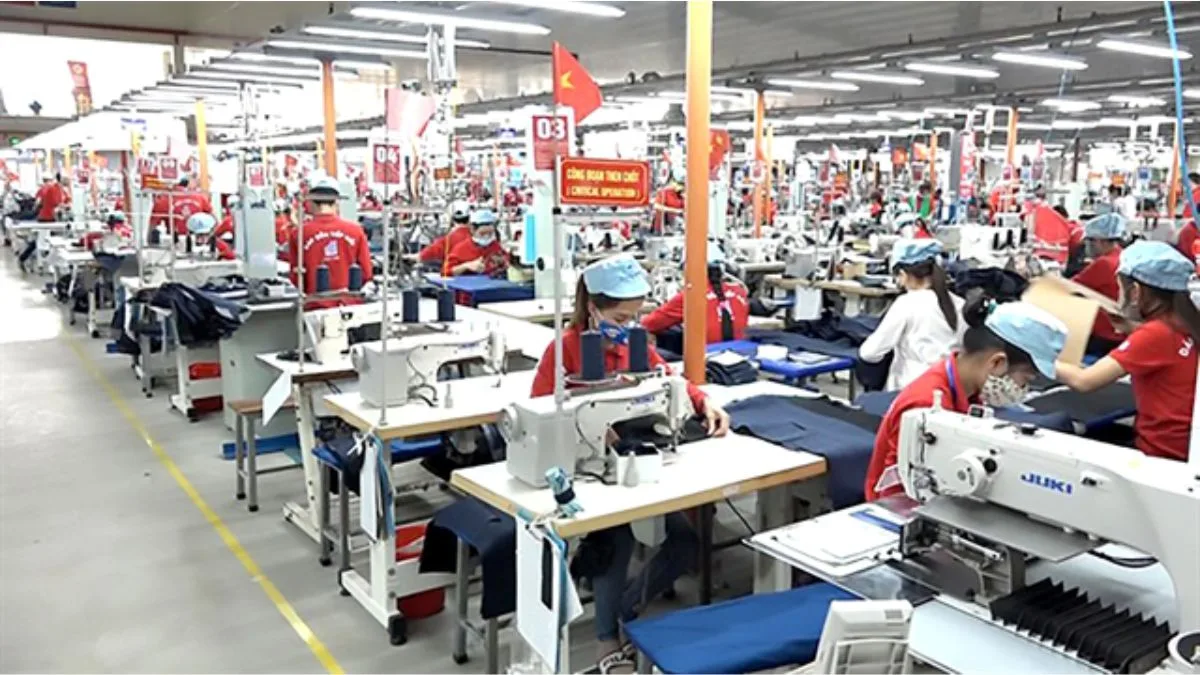
The textile and garment industry in Vietnam is eyeing a potential upturn in the latter part of 2023, contingent upon the pace of recovery in the export market and the adept management of inventory levels by clothing brands. Recent developments in the sector shed light on both challenges and prospects.
After a period of sanguine growth, the textile and garment export sector encountered a protracted deceleration from late 2022 to early 2023. Several factors contributed to this slowdown, including the Russia-Ukraine conflict, geopolitical tensions, inflation, and reduced consumer spending.
In August, textile export turnover in Vietnam reached US$4.06 billion, surpassing the 2022 average of $3.72 billion, signaling a positive turnaround. Notably, orders began to return in the final months of the year.
Thân Đức Việt, General Director of Garment 10 Corporation SJC (M10), highlighted, “For the first time, we received production orders from customer brands in Thailand and the Philippines. Although the number of orders cannot be compared to the size of the US and European markets, it demonstrates the company’s efforts in diversifying global markets.”
Domestic economic factors are also bolstering Vietnam’s textile exports, with decreasing lending interest rates providing businesses the opportunity to access more affordable credit sources and invest in production.
Analysts are cautiously optimistic about the future of Vietnam’s textile exports, with indications of recovery in the fourth quarter, attributed to the depletion of inventories held by US retailers and the growing trend of multinational companies shifting production from China to Vietnam. SSI Research forecasts positive profit growth for businesses as early as the fourth quarter of 2023.
The textile and garment sector is not only vital to Vietnam’s export activities but also comprises a substantial number of listed companies on the stock exchange. Despite some fluctuations, cash flow continued to be directed towards textile and garment stocks from late August to mid-October.
For example, TNG shares of TNG Investment and Trading JSC reached a peak of VNĐ22,300 per share on September 21, before undergoing a slight adjustment. HTG stocks of Hòa Thọ Textile – Garment JSC witnessed a price increase from April until October 16, rising by approximately 50% since the beginning of the year.
Similarly, MSH of Sông Hồng Garment JSC reached VNĐ45,600 per share on October 13, experiencing a significant increase compared to the start of the year.
Viet Dragon Securities Co (VDSC) emphasized that textile and garment companies’ shares are currently trading at trailing P/E levels significantly higher than the historical average, indicating that recovery prospects have already been partially incorporated into stock prices.
The potential price increase of textile stocks in the second half of 2023 largely hinges on the recovery speed of the export market and brands’ inventory management efficiency.
Despite the initial positive stock market performance, the third-quarter results of textile and garment enterprises displayed a decline, contrary to market expectations. Many companies reported negative profit growth or substantial losses for the first nine months of 2023 compared to the same period in the previous year.
In conclusion, the textile and garment industry in Vietnam faces both challenges and opportunities, with a keen eye on the export market’s recovery and the performance of textile stocks in the latter part of 2023.
Reference: Vietnam News
Image Credit: M10


