Shipping performance in the first half (H1) seems negative growth. The market is still uncertain in the second half of this year, though BIMCO (Baltic and International Maritime Council) expects a recovery.
Global container volumes in the first half of 2023 show negative growth as head-haul and regional trade lanes have not yet recovered from the slowdown that began in the second half of 2022, according to BIMCO. Though there is no actual report, some indicators from trade volume among the world’s leading countries have proved it.
BIMCO expects the recovery in volumes and growth rates will begin during the second half of 2023. BIMCO predicts that global container volumes will grow by between 0.5% and 1.5% in 2023 for a good scenario with the growth in the second half.
However, much uncertainty about the timing of the market recovery still exists, forcing BIMCO to develop a low-case scenario. In this scenario, BIMCO assumes that the market downturn will last throughout 2023 and that recovery will only begin in 2024.
In this low-case scenario, global container volumes will end 2024 about 3.5% lower than in the base-case scenario. Volumes in head-haul and regional trade lanes will end 2024 nearly 5% lower than in the base case scenario.
Export-Import Slow Down
Export of the world’s second-largest economy country, China, shrank much faster than expected in May, and imports fell, albeit at a slower pace, as manufacturers struggled to find demand abroad and domestic consumption remained sluggish.
According to Reuters’ report, China’s economy fell 7.5% year-on-year in May, the most significant decline since January and swinging from 8.5% growth in April. Imports contracted 4.5%, a slower pace of decline than the 7.9% in the previous month.
The poor export performance reflects weak demand for Chinese goods, as does the weak import performance as China brings in parts and materials from abroad to assemble finished products for export.
South Korean data showed shipments to China slid 20.8% in May, marking a full year of monthly declines, with Korean semiconductor exports dropping 36.2%, suggesting weak demand for components for final manufacture.
China’s imports contracted sharply in April, while exports rose slower, reinforcing signs of feeble domestic demand despite the lifting of Covid curbs and heaping pressure on an economy already struggling in the face of cooling global growth.
Inbound shipments to the world’s second-largest economy fell 7.9% year on year in April, extending the 1.4% decline seen a month earlier, while exports grew 8.5%, easing from the 14.8% surge in March, China customs data showed.
The downturn in imports suggests the world economy will only be able to count a little on China’s domestic engine of growth. As the nation re-exports some of its imports, it also reinforces the extent of weakness in some of its major trading partner economies.
A 15.3% drop in the import of semiconductors indicates the scale of the demand-pullback in the re-export market for such parts.
Analysts say the sharp global monetary policy tightening campaign of the past 12-18 months and recent Western banking stress remain concerns for the revival prospects of both China and worldwide.
Shipments growth to ASEAN, a block of Southeast Asian countries, slowed to 4.5% in April from 35.4% in March. The region is China’s largest export partner.
Other recent data also showed South Korean exports to China, a leading indicator of China’s imports, were down 26.5% in April, continuing ten consecutive months of decline.
China’s coal imports fell in April from a 15-month high in the prior month, snapping back as demand weakens in the Asian giant. Imports of copper, a proxy for global growth, and natural gas were also down in the same period.
Leading Ports Lower Throughput
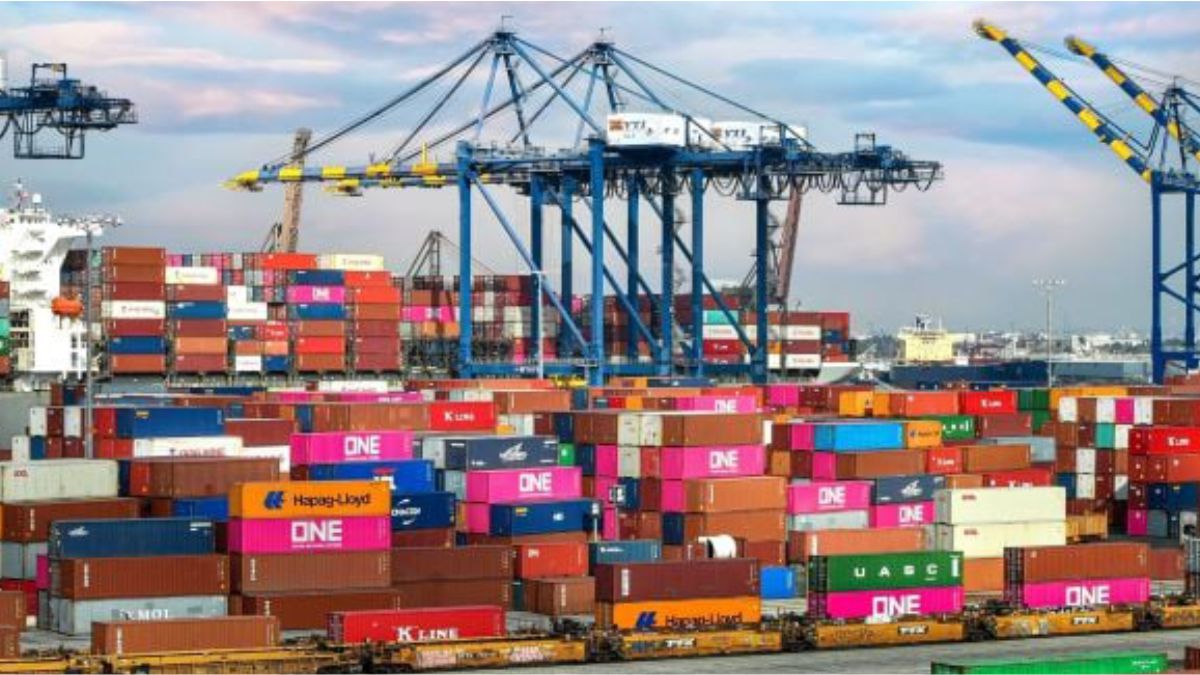
Import cargo volume at US’ major container ports is projected to decrease 22 percent during the first half (H1) of 2023 compared to last year, according to a new report by the National Retail Federation (NRF) and Hackett Associates.
This downturn in cargo volume comes amidst disruptions at key West Coast ports, including the Ports of Oakland and Long Beach.
In April 2023, US ports processed 1.78 million twenty-foot equivalent units (TEUs)— a 9.6 percent increase from March but a 21.3 percent decline Year-on-Year (YoY), per the Global Port Tracker report.
May’s cargo volume is projected at 1.84 million TEUs, reflecting a 23 percent YoY drop, while June’s forecast stands at 1.91 million TEUs, a 15.3 percent decrease from last year. This trend would bring the total for the first half of 2023 to 10.5 million TEUs, a 22.3 percent decrease from the first half of 2022.
The report further forecasts a continued decline in volume for the latter half of the year. July’s import cargo volume is predicted to be 1.99 million TEUs, an 8.8 percent drop YoY, with August at 2.02 million TEUs, down 10.5 percent. September and October are each forecast to handle 1.95 million TEUs, a decrease of 4 percent and 2.7 percent, respectively.
Although a full-year forecast has yet to be made, the report anticipates that the third quarter will total 5.97 million TEUs, a 7.9 percent decrease from last year. The first nine months of 2023 should total 16.48 million TEUs, a 17.6 percent decrease YoY. In 2022, total imports reached 25.5 million TEUs, marking a 1.2 percent decrease from the record-setting 25.8 million TEUs in 2021.
| Shipping Company | Operating Income (Million Dollar) | YoY Change | Net Profit (Million Dollar) | YoY Change |
| Maersk | 14207 | -26% | 2326 | -68% |
| Hapag Lloyd | 6028 | -33% | 1874 | -61% |
| ONE | 4642 | -45% | 1184 | -77% |
| Cosco Shipping Holdings | 6723 | -55% | 1011 | -74% |
| HMM | 1580 | -58% | 216 | -91% |
| Evergreen Shipping | 2172 | -61% | 164 | -95% |
| Yang Ming Marine | 1201 | -65% | 111 | -94% |
| ZIM Integrated Shipping | 1374 | -63% | -58 | -103% |
| Wanhai Lines | 831 | -68% | -68.78 | -105% |
| OOCL | 2176 | -58% | / | / |
Shipping Lower Performance
Recently, major global container shipping companies have successively released their financial reports for the first quarter of 2023. Due to the significant drop in market freight rates and weak demand, the performance of shipping companies in the first quarter of this year could have been better, with the revenue and net profit of various shipping companies dropping significantly compared to the same period of last year. Some shipping companies have suffered losses.
Overall transport demand and market freight rates declined in the first quarter, affecting revenue and profit performance in the first quarter. In addition to paying close attention to the changes in cargo volume in the short-term market, Changrong Shipping will continue to pay attention to changes in the relevant industrial chain and trade structure caused by geopolitical factors and deploy capacity in a timely manner to cope with market development.
Looking to the future, Evergreen said that the overall freight rate and export volume have picked up slightly in April, and the future still depends on global political and economic development, destocking, and the impact of changes in supply and demand in various regions. Evergreen still believes that the market recovery is cautiously optimistic.
Hapag Lloyd’s EBITDA in the first quarter of 2023 was $2.4 billion (2.2 billion euros). Compared with the same period last year, EBIT fell to $1.9 billion (1.7 billion euros), while group profit was also lower on the year, at $2 billion (1.9 billion euros).
Maersk’s first-quarter revenue fell 26% from $19.3 billion to $14.2 billion, earnings before interest, tax, depreciation, and amortization (EBITDA) declined from $9.1 billion to $4 billion, and earnings before interest and tax (EBIT) fell from $7.3 billion to $2.3 billion.
On May 22, 2023, global container shipping company ZIM Integrated Shipping Services Ltd. released its consolidated results for the three months ended March 31, 2023.
Net loss in the first quarter of 2023 was $58 million (compared with net income of $1.711 billion in the first quarter of 2022); adjusted EBITDA in the first quarter of 2023 was $373 million, down 85% from a year earlier; and operating loss of EBIT before interest and tax in the first quarter of 2023 was $14 million, compared with operating profit of $2.243 billion in the first quarter of 2022. Revenue was $1.374 billion in the first quarter of 2023, down 63% on the year.
CMA CGM announced its first-quarter results. Revenue during the reporting period was $12.72 billion, down 30.2% from a year earlier. EBITDA was $3.44 billion, down 61.3% year on year; net profit was $2.01 billion, down 72.1% compared to last year.
Specifically, revenue from the CMA CGM shipping business fell 40.3% year-on-year to $3.05 billion, down 64.3% from a year earlier. Revenue from the logistics business was $3.86 billion, up 14.1% annually. EBITDA was $340 million, up 36.9% on the year. In addition, in the first quarter, CMA CGM cargo volume was 5.02 million TEU, down 5.3% from a year earlier. The average freight was $1766 /TEU, down 37% on the year.
This article was published in ISG Print Magazine July 2023 Edition.